First Steps After Roof Storm Damage
After a storm, take photos of the roof, the yard and every interior stain before anything is moved, and keep the receipts for tarps or emergency repairs. We photograph and write up the damage for your own claim, which gives your insurer a clear record of what the storm did and what it did not.
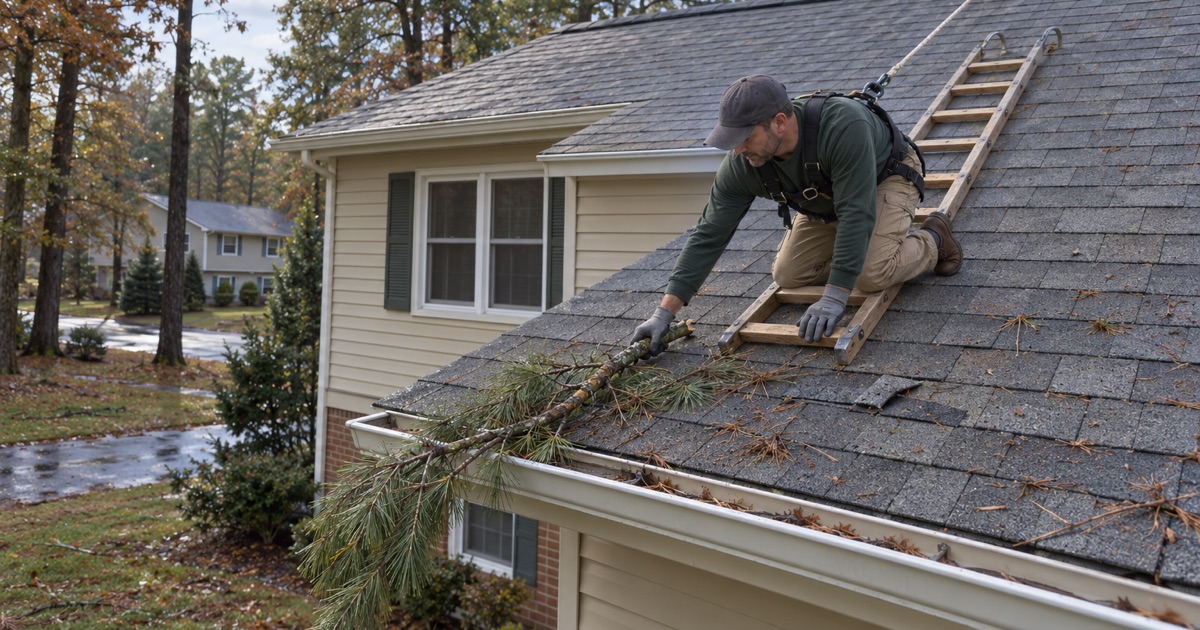
A Tree or Large Limb on the Roof
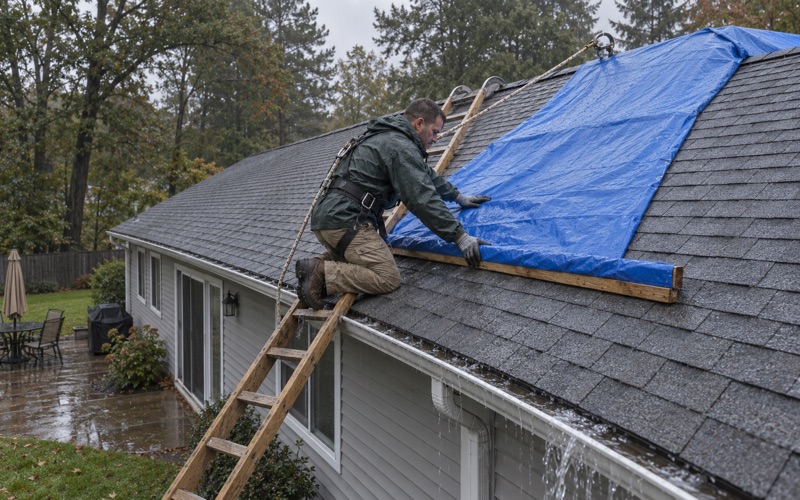
In the first hour, get everyone out of the rooms under the impact and stay off the roof. Call the utility if wires are involved and your insurer to report the loss, then call us to tarp the opening once a tree crew has the weight off. Jackson saw exactly this kind of damage when two EF-2 tornadoes crossed the township on April 1, 2023.
How a Homeowners Roof Claim Works in New Jersey
You report the loss to your insurer, an adjuster inspects, and the company issues a settlement based on your policy’s coverage and deductible. We document the damage and, when you ask, meet the adjuster on the roof to point out what we found, while the claim itself stays between you and your insurer.
Wear and Tear Versus Storm Damage
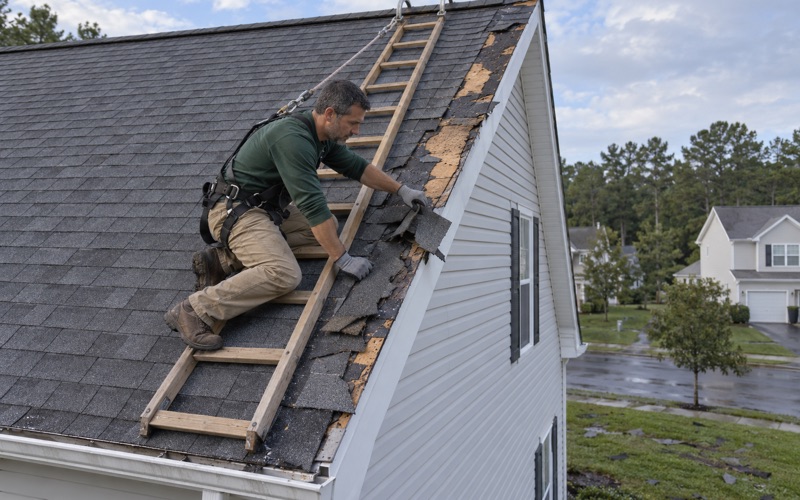
Insurance pays for sudden damage, such as lifted shingles, punctures from limbs or tabs torn off in a gust, but not for a roof that is simply worn out. Claims get denied when the damage looks like age rather than an event, which is why we photograph the specific storm damage separately from the roof’s general condition.
The New Jersey Hurricane Deductible
A hurricane deductible is a separate, larger deductible, typically two to five percent of a property’s insured value according to the state. Under DOBI Bulletin 11-16 it applies only to a hurricane named by the National Weather Service with sustained winds of 74 mph or more in New Jersey, which is why the state barred it for Sandy, classified as post-tropical before landfall.
Public Adjusters in New Jersey
Anyone paid to negotiate a property claim for a homeowner must be a public adjuster licensed by the Department of Banking and Insurance under N.J.S.A. 17:22B. Their fee is set in a written contract, usually as a percentage of the settlement, and a roofer cannot legally fill that role, which is why we document damage but leave negotiation to you or a licensed adjuster.
New Jersey Sales Tax on a Roof
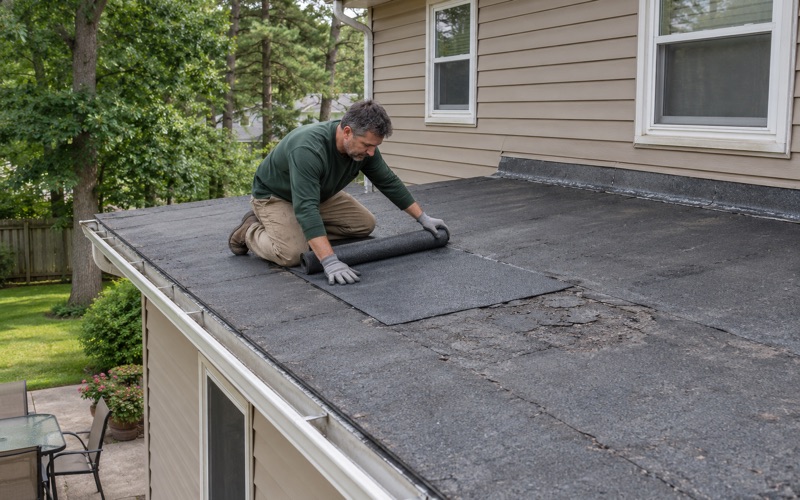
The state treats a new roof as an exempt capital improvement, documented on Form ST-8, while fixing a leaky roof or repairing gutters is taxable repair work. That difference is why we show replacement and repair on separate paperwork, so you are not charged sales tax on a capital improvement.
What a Roof Replacement Costs in Jackson
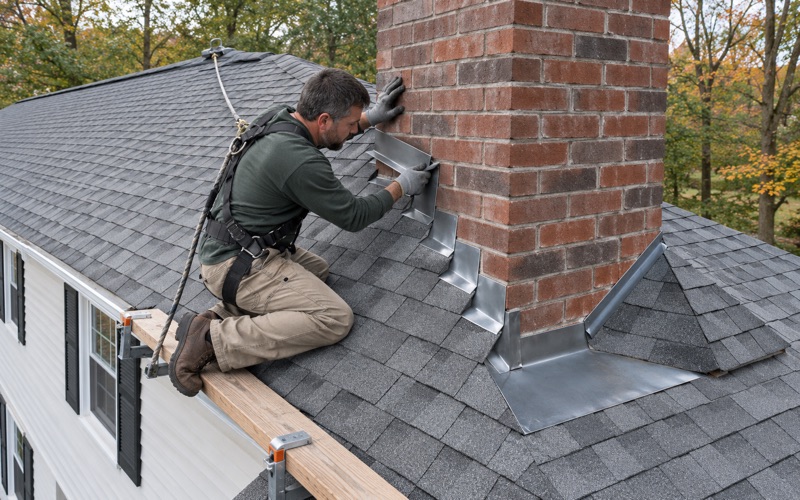
Price depends on the size and pitch of the roof, the number of layers coming off, how much decking needs replacing, the shingle line, flashing and ventilation work, and access. Our itemized scope shows each of those as its own line, so you can see which factors move your number and decide where to spend.
Insurance on a 20-Year-Old Roof
Many policies treat an older roof differently from a new one, sometimes settling roof claims on depreciated value rather than replacement cost. Read the roof section of your declarations page before storm season, and if the roof is near the end of its life, a planned replacement may cost less than discovering the limit after a storm.
Why the 25 Percent Rule Is Florida’s, Not New Jersey’s
The rule that a roof must be replaced once more than 25 percent of it is repaired comes from the Florida Building Code. New Jersey once had a 25 percent limit on roof repairs counted as ordinary maintenance, but it was deleted in 2018, and the state’s rehabilitation subcode uses layer count and material, not a percentage, to decide when a tear-off is required.
Roofing License or Contractor Registration in New Jersey
New Jersey has no separate roofing license. Contractors doing residential roofing work register as home improvement contractors under the state’s Contractors’ Business Registration Act, and you can look up a registration with the Division of Consumer Affairs before signing. Ask any roofer you are considering for the registration number and certificate of insurance.